Quality for insurance companies
What makes a strong business?
A good business needs more than a good year. The Quality score looks at how well the company uses its money, earns profit and supports its finances.
Customer payments for insurance are called premiums. Claims are the costs of covered damage or losses.
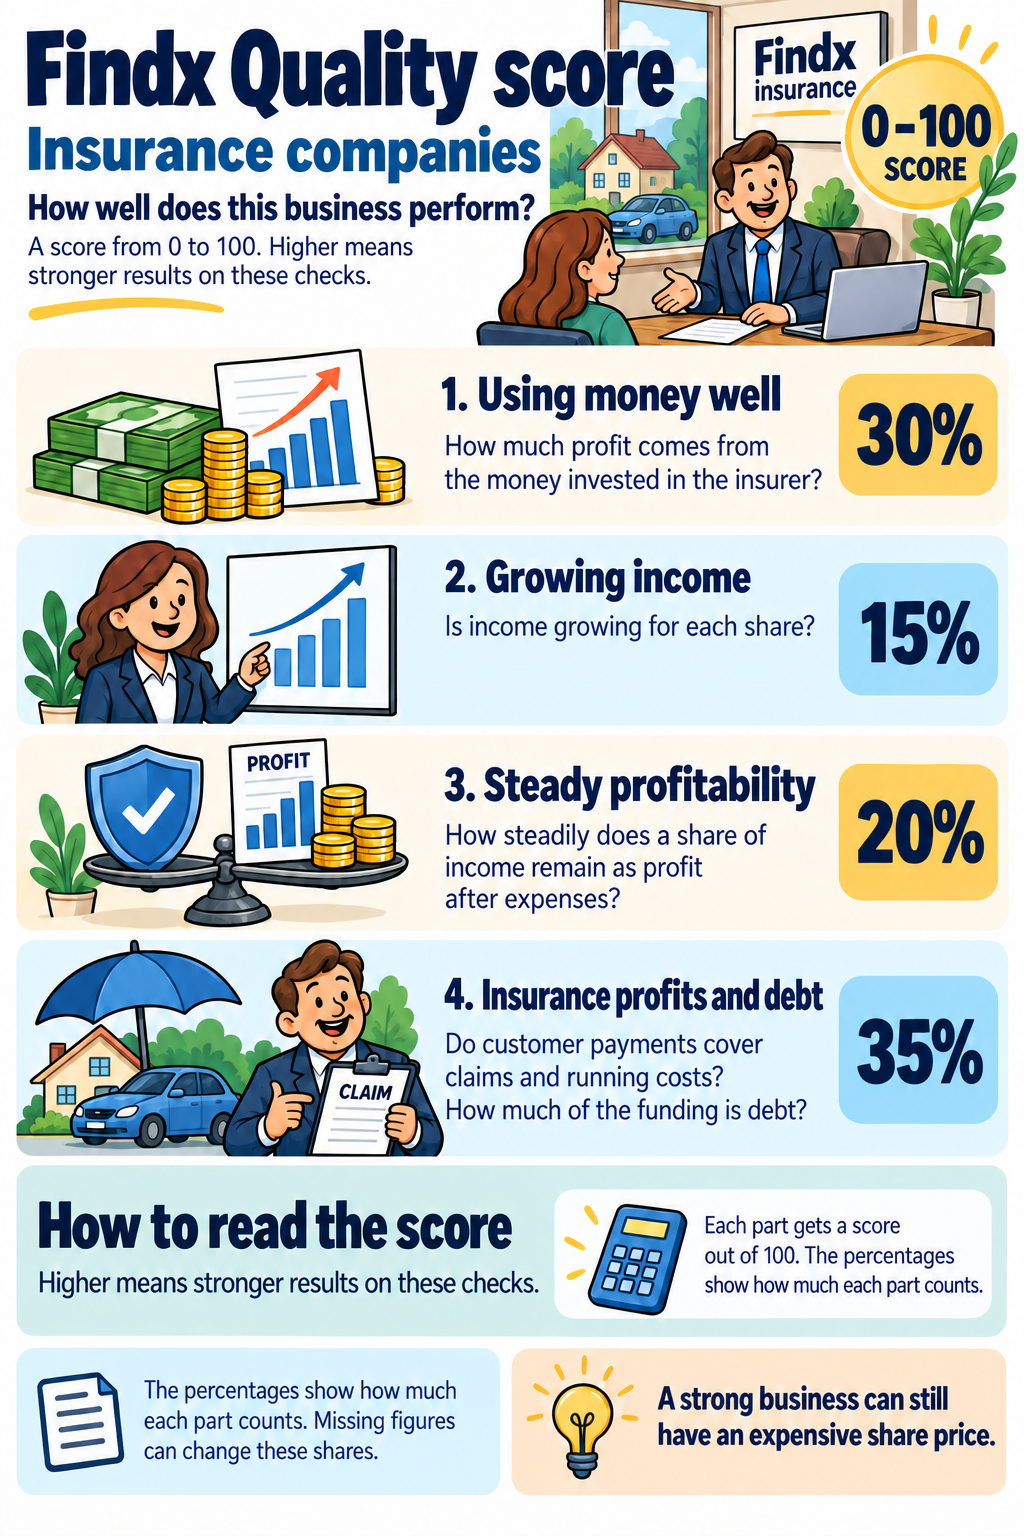
4 parts. One score from 0 to 100.
The score describes the business. It does not tell you whether the shares are cheap.
What does the number tell you?
A higher score means stronger results on these checks.
Each part receives points from 0 to 100. The percentages above show how much each part counts. A higher total means stronger results on these checks.
Questions behind the score
The percentages show how much each part counts. How much profit comes from the money invested in the insurer? This describes a return in the business, not the return you receive on your shares. Is income growing for each share? Using an amount per share allows for changes in the number of shares. How steadily does a share of income remain as profit after expenses? Steady positive profits are more reassuring than results that swing sharply. Do customer payments cover claims and running costs? How much of the funding is debt? This is the insurance result before investment income. We also look at how steady it has been.Using money well
See how the points are calculated
Growing income
See how the points are calculated
Steady profitability
See how the points are calculated
Insurance profits and debt
See how the points are calculated
Missing figures reduce the information supporting the score and may change how much each remaining check counts. With too little usable information, no score is shown. Read the notes beside the company’s score. A usable return measure is required.
How we calculate the points
Explore the calculation, the periods used and the information behind the result. Here we emphasise whether insurance operations earn money and how much debt the company carries. The standard cash-generation component is not used in this calculation. This does not mean insurers have no cash flows. A poor result and a missing figure are different things. A poor result lowers its part of the score. When a figure is missing, the other parts may receive more weight. We also show that the assessment is based on less information. We measure how much of the calculation has usable information. We use the component weights, so a missing measure with a large share matters more. At least 90% normally gives High confidence, 70% to below 90% gives Medium, and 60% to below 70% gives Limited. Confidence can be lower when some figures rely on an alternative calculation. We do not show an overall Quality score if usable information covers less than 60% of the calculation. We also need a usable return-on-capital measure. Without it, we do not show the score. For a bank, we use the corresponding bank return measure. A measure that is not used for that business type does not count as missing. For example, we do not assess a bank using the standard free cash flow calculation.How the checks add up
Insurance companies
What happens when figures are missing?
What happens when figures are missing?