When sales slow down, the bills still arrive. The Strength score looks at debt, cash and profit to help you see how well a business is equipped to cope.
This guide applies to most businesses, including shops, manufacturers and software companies.
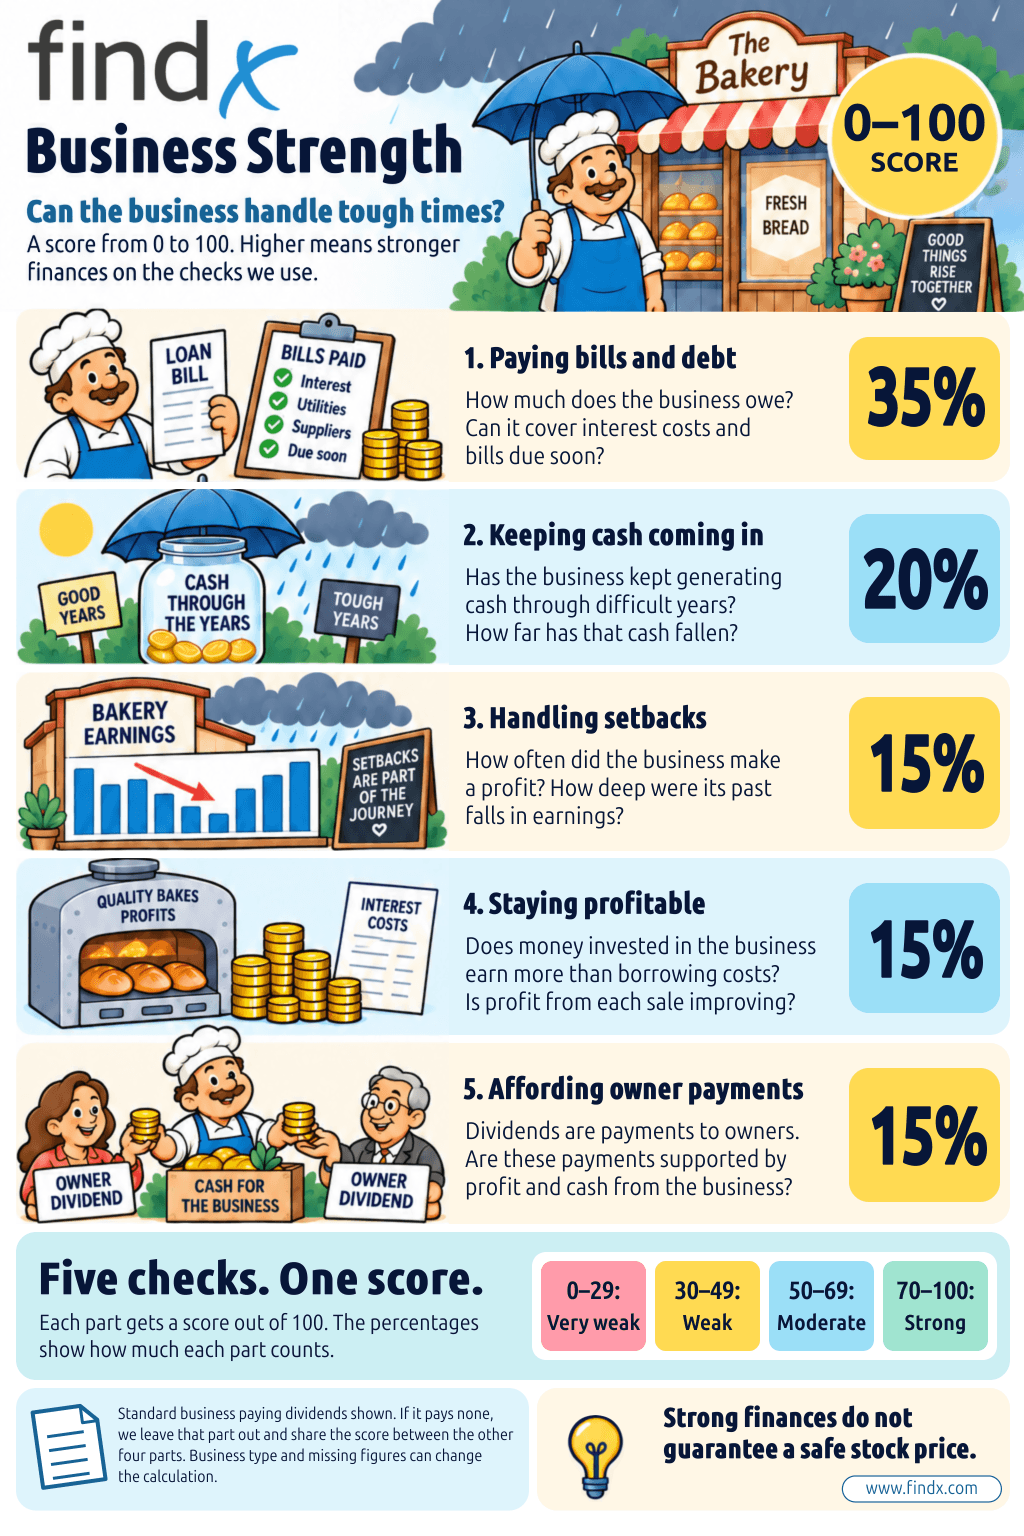
5 parts. One score from 0 to 100. The score describes the business. It does not tell you whether the shares are cheap.
Paying bills and debt 35%Keeping cash coming in 20%Handling setbacks 15%Staying profitable 15%Affording owner payments 15%
70–100 means strong, 50–69 moderate, 30–49 weak, and 0–29 very weak. A good total can still come with a warning about a specific weakness.
02 / Explore the business
Questions behind the score
The percentages show how much each part counts.
01
Can it keep paying the bills?
Can the business support its debt, interest and bills due soon?
35%of the score
A simple example
$10 million profit÷$2 million interest=5× covered
Profit could fall before the interest bill becomes hard to cover.
See how the points are calculated
In the calculation: Debt and ability to pay
▸Long-term borrowingWe compare long-term debt with the capital financing the business. If $40 of every $100 comes from long-term borrowing, the ratio is 40%. A smaller debt share gives the company more room when results weaken.Counts for 20% of this part of the score. Points: 0% gives 100 points; 70% gives 0.
▸Ability to pay interestWe compare operating profit with interest costs. If profit is $10 million and interest costs are $2 million, profit covers interest five times. A larger buffer means profit can fall further before interest becomes difficult to cover.Counts for 30% of this part of the score. Points: 2× gives 0 points; 5× gives 100.
▸Resources for bills due soonWe compare short-term assets, such as cash, customer payments due and inventory, with debts due within a year. A ratio of 2 means $2 of assets for every $1 owed. More cover gives room to meet bills, although inventory and unpaid customer invoices are not cash yet.Counts for 15% of this part of the score. Points: 1× gives 0 points; 2× gives 100.
▸Debt after subtracting cashWe subtract the company's cash from its debt and compare the remainder with EBITDA: earnings before interest, tax, depreciation and amortisation. The last two are accounting charges for using up assets over time. A ratio of 3 means net debt is three times that annual earnings measure. Lower is better because the remaining debt is smaller relative to the earnings supporting it.Counts for 15% of this part of the score. Points: 0× gives 100 points; 4× gives 0.
▸Debt after allowing for investment spendingWe subtract spending on buildings, equipment and similar assets from EBITDA, then compare debt with what remains. This checks whether debt still looks manageable when the business also needs to invest. A smaller ratio is stronger. The amount left is an adjusted earnings measure, not cash available solely for debt repayment.Counts for 10% of this part of the score. Points: 1× gives 100 points; 4× gives 0.
▸Debt compared with cash from operationsWe compare total debt with the cash generated by day-to-day operations over a year. Debt of $300 million and operating cash flow of $100 million gives a ratio of 3. Lower means less debt relative to cash generation. It does not mean the debt will be repaid in three years, because the cash also has other uses.Counts for 10% of this part of the score. Points: 2× gives 100 points; 7× gives 0.
02
Does cash keep coming in?
How often did operations generate cash? How deep were the falls, and was profit backed by cash?
20%of the score
A simple example
Cash generated in6 of 8 years=75%
More years with cash coming in show a more reliable business.
See how the points are calculated
In the calculation: Profit and cash through difficult years
▸Years when operations generated cashWe count how many of the financial years examined had more cash coming in from day-to-day operations than going out. If this happened in six of eight years, the share is 75%. More years with positive operating cash flow show that the business generates cash more reliably.Counts for 24% of this part of the score.
▸Years with cash left after investmentWe count the years when cash from operations exceeded spending on assets such as buildings and equipment. In those years, the business had free cash flow left for other purposes. More such years show that it has regularly covered both operations and investment from its own cash generation.Counts for 16% of this part of the score.
▸Largest fall in cash from operationsWe find the largest fall from an earlier high to a later low in annual operating cash flow. A fall from $100 million to $60 million is 40%. Smaller declines mean the business has kept more of its cash generation during weak periods.Counts for 24.5% of this part of the score.
▸Largest fall in cash left after investmentWe find the largest decline in annual cash remaining after investment in assets. A smaller fall means this financial room has held up better. We give this less weight than operating cash flow because a major investment can temporarily reduce the money left, even when the business is healthy.Counts for 10.5% of this part of the score.
▸Cash behind the profit in the weakest yearAccounting profit does not always arrive as cash in the same year. We find the weakest usable year for cash from operations compared with profit. If profit was $100 million but operations generated only $50 million in cash, the ratio was 0.5. A higher weakest-year ratio means cash supported profit better even in that year.Counts for 25% of this part of the score. Points: 0.2× gives 0 points; 0.8× gives 100.
03
How well has it handled setbacks?
How often was the business profitable? How deeply did earnings per share fall?
15%of the score
A simple example
Profit per share$10 → $4=60% fall
The score checks the size of past setbacks as well as how often the business made a profit.
See how the points are calculated
In the calculation: Sensitivity to downturns
▸Years with a profitWe count how often the company reported a positive profit per share during the years examined. A company that was profitable in all eight years has a stronger record here than one profitable in only four. This checks how often the business avoided losses, not how large its profits were.Counts for 50% of this part of the score. Points: 40% gives 0 points; 100% gives 100.
▸Largest fall in profit per shareWe measure the largest decline from an earlier high to a later low in profit per share. A fall from $10 to $4 per share is 60%. Smaller falls mean earnings have held up better when the business weakened.Counts for 50% of this part of the score. Points: 10% gives 100 points; 80% gives 0.
04
Can it keep earning a profit?
Do returns exceed borrowing costs? Is profit from each sale improving?
15%of the score
A simple example
Of every $100 in income$10 → $12left as profit
More profit from the same income means the profit margin has improved.
See how the points are calculated
In the calculation: Lasting profitability
▸Return compared with borrowing costWe compare the return earned in the business with its estimated borrowing cost after tax. A return of 12% and a borrowing cost of 4% leave a gap of 8 percentage points. A larger gap is stronger here. We average the yearly gaps to avoid relying on just one year; this comparison does not include the return shareholders require. For this company type we use return on invested capital (ROIC): profit after tax from running the business compared with the money invested in it.Counts for 66.67% of this part of the score. Points: 0 percentage points gives 0 points; 8 percentage points gives 100.
▸Is profitability improving or weakening?We examine how the company's profit margin has changed over several years. A margin shows how much of its income becomes profit. A rise from 10% to 12% means $2 more of every $100 in income is left as profit. A rising margin strengthens this part of the score; a falling one weakens it.Counts for 33.33% of this part of the score. Points: −2 percentage points per year gives 0 points; +2 percentage points per year gives 100.
05
Can it afford payments to owners?
Are dividends, payments to owners, supported by profit and cash from operations?
15%of the score
A simple example
$4 paid to owners÷$10 profit=40% paid out
Paying out a smaller share of profit leaves more room if earnings fall.
See how the points are calculated
In the calculation: Ability to support the dividend
▸How much of the profit is paid out?We compare dividends with profit from the same period. If profit is $10 per share and the dividend is $4, the company pays out 40% of its profit. A smaller payout share leaves more room to keep paying if earnings fall.Counts for 66.67% of this part of the score. Points: Up to 40% payout gives 100 points; 60% gives 80; 80% gives 40; 100% or more gives 0.
▸Cash available to cover dividendsWe compare cash from operations with the dividend payment. If operations generate $200 million and dividends cost $100 million, cash covers the dividend twice. Higher coverage leaves more room, but investment in assets must also be financed from this cash or other sources.Counts for 33.33% of this part of the score. Points: 1× gives 0 points; 2× gives 100.
The percentages assume the company pays dividends. Dividends are payments to owners. If it pays none, we leave out that part and share the score between the other four parts in the same proportions.
Missing figures reduce the information supporting the score and may change how much each remaining check counts. With too little usable information, no score is shown. Read the notes beside the company’s score. Enough information about debt and payment capacity is also required.
03 / Look a little closer
How we calculate the points
Explore the calculation, the periods used and the information behind the result.How the checks add up
Ordinary companies
For most businesses, we use the measures below. The percentages in this list are shares of the named part, not shares of the total score. For example, interest coverage is 30% of the debt part, which itself counts 35% overall.
Cash from operations is money generated by day-to-day business. Free cash flow is what remains after spending on assets such as buildings and equipment. Cash conversion compares cash from operations with accounting profit.
Debt checks look at both the amount owed and the ability to carry it. Interest coverage gets the largest share because interest is a recurring bill. The other checks add short-term payment capacity and different views of the debt burden.
In the cash-history part, positive years count 40%, the largest cash declines 35%, and the weakest cash conversion 25%. Cash from operations counts more than free cash flow within the first two checks, because investment spending can temporarily reduce free cash flow.
For downturn sensitivity, profitable years and the deepest earnings fall count equally. For lasting profitability, returns above borrowing costs count two thirds and the margin trend one third. Dividend payments are checked mainly against profit, with cash adding a second check.
The finer details
Points change gradually between the stated values. A percentage-point gap means simple subtraction: a 12% return minus a 4% borrowing cost is 8 percentage points. For this check, we average the yearly gaps over up to five years, using at least three years with both figures available. This compares returns with borrowing costs only. It does not include the return shareholders require.
For ordinary companies, tax figures affect both ROIC and the estimated borrowing cost after tax. An unusual tax expense or benefit can change the comparison for one year. We use up to five years to reduce the influence of that year.
We use adjusted profit per share when enough history is available; otherwise we may use diluted earnings per share (EPS) and state that. This means profit divided by the number of shares, allowing for potential extra shares. A year with both a loss and negative cash from operations counts as a weak cash-conversion result. A loss with positive cash does not give a useful cash-to-profit ratio, so that observation is left out. Missing information is never treated as a good result.
For the history checks, the largest decline means the fall from an earlier high to a later low within the years examined. Positive-year checks score from 0 when 40% or fewer years are positive to 100 when all are. Ordinary earnings and cash declines score 100 at 10% or less and 0 at 80% or more. We do not infer the cause of a decline from its size alone.
Which years do we look at?
Which years do we look at?
To see how the business handled difficult years, we look back over up to eight full financial years. For lasting profitability, we use up to five. Most historical checks need at least three usable years. With only three or four, confidence is Limited.
For current debt and dividend checks, we use the latest 12 months, often called TTM. If those figures are missing, we use the latest full financial year. A ratio always compares figures from the same period.
We do not count a rolling 12-month total as an extra financial year. We also do not pull in older years to fill gaps. The cards show the periods used.
How much information supports the score?
How much information supports the score?
Data coverage tells you how much of the planned calculation we can support with usable figures, taking each measure's share into account.
High: at least 90% coverage. Good: at least 70%. Limited: at least 60%. We also need at least 60% of the debt part to be measured. Without that debt information, or below 60% overall coverage, we show no score.
Short histories of three or four years, certain substitute measures, and the insurance and financial-services methods limit confidence to Limited. The label describes the information supporting the score, not a guarantee about the future.
The one idea that matters most in Findx
It is important that you understand how Findx arrives at Fair Value. Please take a minute to watch this short explainer.
It is very important that you understand this
Fair Value is an estimate, and you choose the basis it is built on. Do not invest based on our default without understanding how we calculate it.